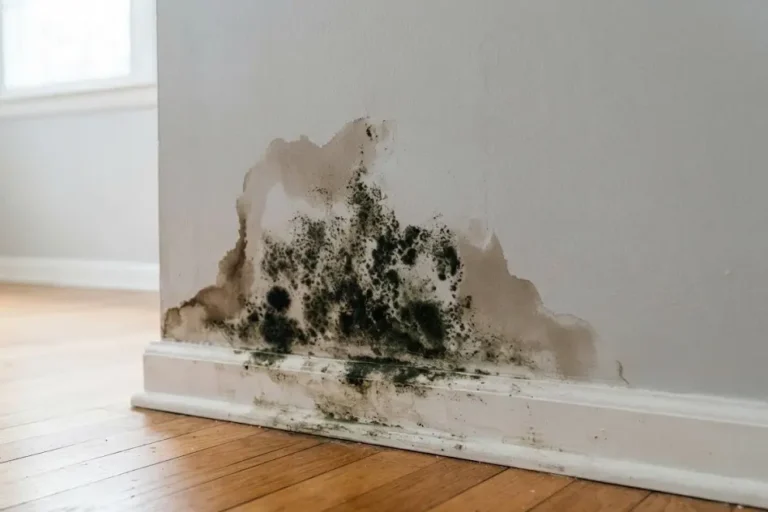
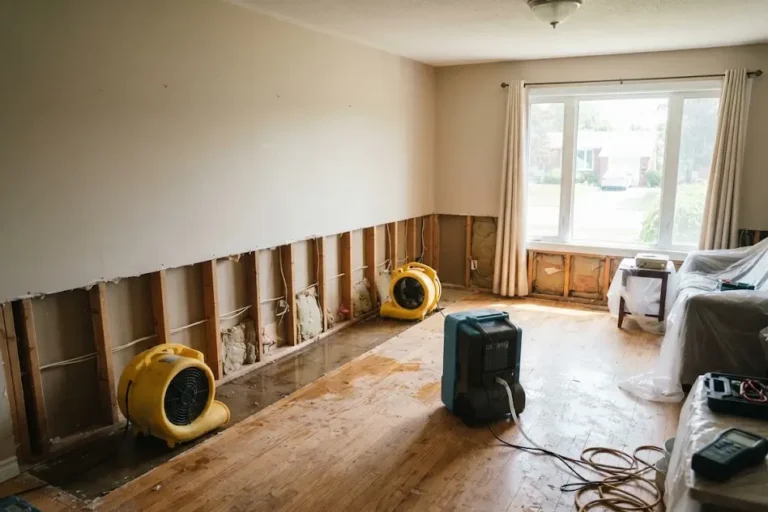
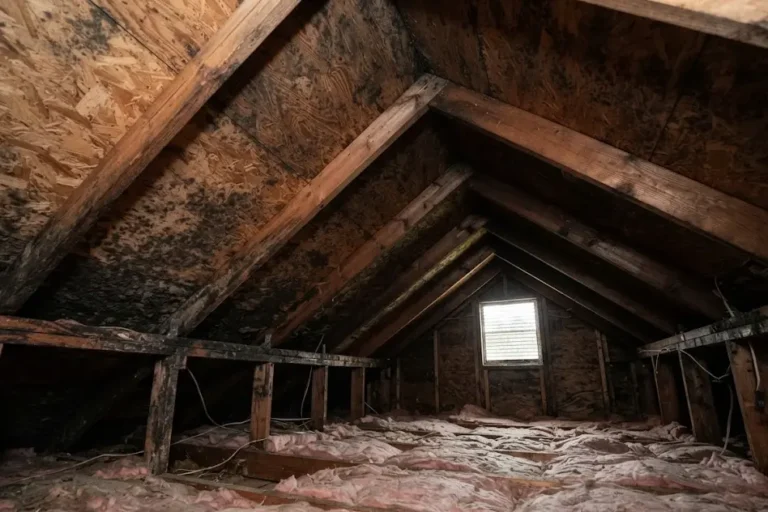
$1,200 – $9,000Insurance covers mold usually only when it is the result of a sudden, accidental water loss your policy already covers, such as a burst pipe or an overflowing washer hose, and not when it comes from a slow leak, poor ventilation, poor upkeep or a flood (Texas Department of Insurance; Triple-I). So does insurance cover mold removal in full when the claim is accepted? Often not: many policies cap mold payouts at $1,000 to $10,000 (NerdWallet). The range above is what a typical remediation job costs in 2026 across three cost guides, and a whole house can reach $10,000 to $30,000 (Fixr; This Old House), so the gap between the bill and the cap is yours.
Whether a mold claim gets paid turns on one question: what caused the water? This guide sets out which causes are usually covered, how much a policy typically pays when they are, what flood insurance and renters insurance do and don’t pay for, and how to file and document a claim so it is judged on the facts. It explains how coverage generally works according to state insurance regulators and published guides; it is not legal advice, and your own policy wording decides your claim.
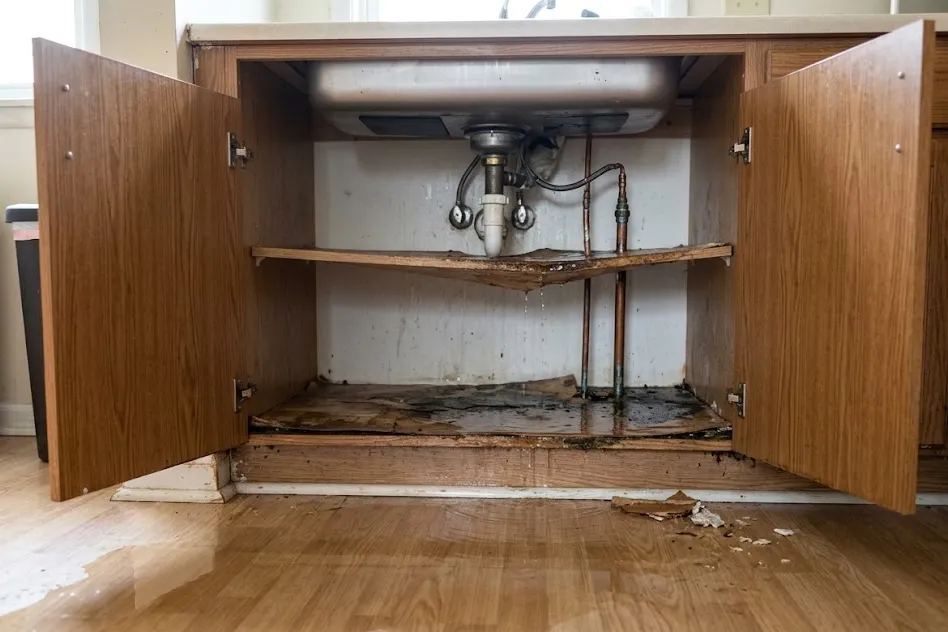
What mold remediation costs if you pay it yourself
| Job | HomeGuide | Fixr | This Old House |
|---|---|---|---|
| Typical job | $1,500 – $6,000 | $1,500 – $9,000 (average $3,500) | $1,200 – $3,750 (average $2,300) |
| Per square foot of affected area | $15 – $30 | $10 – $30 | $10 – $25 |
| About 100 sq ft | $500 – $1,500 (10–100 sq ft) | $1,000 – $3,000 | $1,000 – $2,500 |
| About 200 sq ft | $1,500 – $6,000 (100–300 sq ft) | $2,000 – $6,000 | $2,000 – $5,000 |
| About 500 sq ft | $6,000 – $15,000 (300–1,000 sq ft) | $5,000 – $15,000 | $5,000 – $12,500 |
| Whole house or 1,000+ sq ft | $15,000 – $30,000 | $10,000 – $30,000 | $10,000 – $30,000 |
The guides agree closely at the small and whole-house ends and drift apart in the middle: for about 200 square feet, This Old House tops out at $5,000 and the other two at $6,000. Rebuilding is billed on top. HomeGuide prices drywall replacement at $1.50 to $3.50 per square foot, painting at $1 to $3, insulation at $1.00 to $4.50 and carpet replacement at $2 to $8, and a professional mold inspection at $300 to $650 for an average-sized home (HomeGuide). Our full breakdown by room and job size is in the mold remediation cost guide.
Our estimate: the $1,200 – $9,000 headline is the lowest and highest “typical job” figure among the three guides (This Old House’s low, Fixr’s high). It is a span of published figures, not a measured price, and it is the cost before any insurance payment.
Estimate your mold remediation bill
Our estimate: the published ranges above multiplied out for your inputs. Not a quote. Ranges from HomeGuide (Feb 2026), Fixr (Aug 2025) and This Old House (Mar 2026). This is the full bill before insurance. If the mold is covered, a policy pays up to its mold limit, often $1,000 to $10,000, and your deductible still applies (NerdWallet, Jun 2026). State adjustment: BLS construction wages (May 2025), applied to an assumed 50% labor share. How we calculate
The calculator shows the whole bill, because that is the number a claim is measured against. To see what you might pay, compare it with the mold limit on your declarations page or policy, as the next sections explain.
Covered or not: common causes of mold
| What caused the water | Standard home policy | Source |
|---|---|---|
| Burst pipe, toilet overflow, broken washer hose | Usually covered, including mold on the damaged items | Texas DOI |
| Frozen pipe that bursts | Usually covered if you heat the home properly | Washington OIC |
| Sudden appliance or water heater leak; water used to put out a fire | Usually covered | NerdWallet; Experian |
| Storm damage to the roof, or ice dams | Usually covered, but not if you delay the repair | Washington OIC; Experian |
| Gradual leak or seepage, dripping faucet, leaking foundation | Usually not covered | Texas DOI; Washington OIC |
| Lack of ventilation, poorly sealed windows, overflowing gutters, neglect | Not covered: treated as maintenance | Triple-I; Experian |
| Hidden leak behind a wall that grows mold over time | Probably not covered; some insurers sell hidden water damage coverage | NerdWallet |
| Sump pump failure, sewer or drain backup | Not covered without a water backup add-on | Triple-I; NerdWallet |
| Flood (rising water from outside) | Not covered; needs a separate flood policy, which pays for mold only in limited cases | Texas DOI; Triple-I |
The logic behind the table is the same everywhere. The Insurance Information Institute groups mold with rot and insect infestation as a home maintenance issue that standard policies generally don’t cover, while mold that is the direct result of a covered peril such as a burst pipe may be (Triple-I). Washington’s regulator puts it the same way: insurers often consider mold and rot your responsibility unless they come from water damage your insurance covers (Washington OIC).
Even a covered event does not pay for everything. NerdWallet notes that a standard policy will likely pay to remove the mold and repair the damage it left, but probably not to fix the broken appliance or pipe that caused it (NerdWallet). Replacing a failed tank, for example, is a separate cost; see our guide to water heater replacement cost. The Texas Department of Insurance adds that most home policies don’t include mold cleanup and testing after the damaged item itself has been removed (Texas Department of Insurance).
How much a policy pays for mold: the sublimit
| Source | What it says about mold limits |
|---|---|
| NerdWallet (June 2026) | Insurers usually cap mold payouts at $1,000 – $10,000, and your deductible applies to the claim |
| Insurance.com (January 2026) | A restoration industry manager it quotes says policies typically state a maximum of $1,000 – $10,000 for mold remediation, and that carriers offering mold coverage typically start around $2,500 – $5,000 |
| Experian (September 2026) | Policies that do cover mold typically limit the payment to $5,000 |
| Florida Department of Financial Services (undated) | A mold property endorsement lets you raise the mold limit to $25,000 or $50,000; insurers may offer other limits |
The three guides agree on the shape, a cap well below the cost of a large job, and differ only on where it usually sits. Your own limit is printed in your policy, and it can differ by insurer and by state, so treat the table as a reason to look rather than as your number.
Our estimate: take a covered burst pipe that leaves about 300 square feet of mold. At Fixr’s per-size prices that job costs $3,000 to $9,000. With a $5,000 mold limit, the typical figure Experian reports, the part above the cap could be up to $4,000, and the deductible comes on top. With a $10,000 limit the whole job would fit under the cap. This is an illustration built from the figures above, not a quote; how a deductible and a mold limit interact depends on the policy wording.
Small jobs raise the opposite question: is a claim worth filing at all? NerdWallet works through an example in which an average remediation of $2,368 (an Angi figure) meets a $2,000 deductible, leaving the insurer to pay $368, and notes that filing a claim often leads to higher premiums (NerdWallet). A claim makes more sense when the mold comes with other water damage, or when the job is far bigger than the deductible.
Mold endorsements and other add-ons
An endorsement, also called a rider, is an amendment that adds, deletes, excludes or changes coverage in a policy. The National Association of Insurance Commissioners notes that many home policies exclude mold or sump pump overflow and that an endorsement could add that protection (NAIC, older page, August 2019). Three kinds matter for mold:
- Mold property coverage. In Florida, the state’s consumer pages describe a property endorsement that raises the mold limit to $25,000 or $50,000, and a separate mold liability endorsement that pays claims from others who say your mold made them ill (Florida DFS). Texas notes that some insurers let you add coverage for mold cleanup caused by a covered loss (Texas Department of Insurance), and Washington says that if you don’t have mold coverage you may be able to add it (Washington OIC).
- Water backup and sump pump coverage. Sewer backups are not covered by a typical homeowners policy or by flood insurance, and the coverage has to be bought separately or as an endorsement (Triple-I). NerdWallet adds that it can pay for water and mold damage from a backed-up drain or broken sump pump, but likely not for gradual seepage through the foundation (NerdWallet).
- Hidden water damage coverage. Pays for damage from leaks you can’t see, such as a pipe that bursts behind a wall, and may cover mold cleanup, but not every insurer sells it (NerdWallet).
Florida’s regulator also points out that endorsements adding coverage may carry their own separate deductible (Florida DFS). Ask for the premium, the limit and the deductible of each option in writing.
Flood insurance and mold
Homeowners policies exclude floods, so mold from a flood is not covered by them; that takes a separate flood policy (Texas Department of Insurance). Flood insurance itself is narrow on mold. The Insurance Information Institute says federal flood insurance may cover mold and mildew damage, but only if it is directly attributable to a flood (Triple-I). FEMA’s National Flood Insurance Program lists damage caused by moisture, mildew or mold that the owner could have avoided among the things a policy does not cover (FloodSmart), and its recovery checklist tells policyholders that NFIP policies don’t cover mold damage and to start drying damaged items as soon as possible (FloodSmart).
What the flood policy does pay for is prevention. FEMA’s claims handbook says the policy will not pay to test for mold, identify its type, recommend a remediation protocol or remediate it, including HEPA machines; coverage is limited to removing non-salvageable flood-damaged building materials and applying an anti-microbial to prevent mold and mildew (FEMA NFIP Claims Handbook, older guide, August 2024). The same handbook tells policyholders to remove wet, non-salvageable building materials and belongings to avoid mold growth, but not to discard anything before the adjuster has seen it unless it is a health hazard or local law requires it; if you must, photograph it first.
Renters and landlords
Renters policies follow the same sudden-versus-gradual rule as home policies (Texas Department of Insurance), but they protect different things. A landlord’s insurance protects the building; it won’t replace a tenant’s belongings or pay their living expenses while the building is repaired. Renters insurance covers personal belongings against water and the other disasters listed in the policy, and floods are not included (Triple-I). In other words, a tenant’s own belongings are insured, if at all, by the tenant’s renters policy, while the building is the landlord’s to insure.
Who has to fix the building is a matter of state landlord-tenant law, not insurance. Washington is one example: its Department of Health tells renters to run heating and ventilation to reduce condensation and to notify the landlord promptly, in writing, of leaks or moisture from building problems; landlords there must fix those building problems and give tenants information about mold (Washington State Department of Health). Check the rules where you live.
How to file a mold claim and document it
State regulators give consistent instructions. Follow your insurer’s own steps as well, since the policy sets the conditions.
- Stop the water. Shut it off at the main valve or the valve under the sink or appliance, and start drying the area; Texas notes that mold can start growing within a day after a leak (Texas Department of Insurance).
- Report it quickly. You usually must report water damage that was hidden from view within days of first seeing it (Texas Department of Insurance). California advises reporting any water damage to your agent or company immediately and contacting the claims adjuster right away if you suspect mold after a leak (California Department of Insurance).
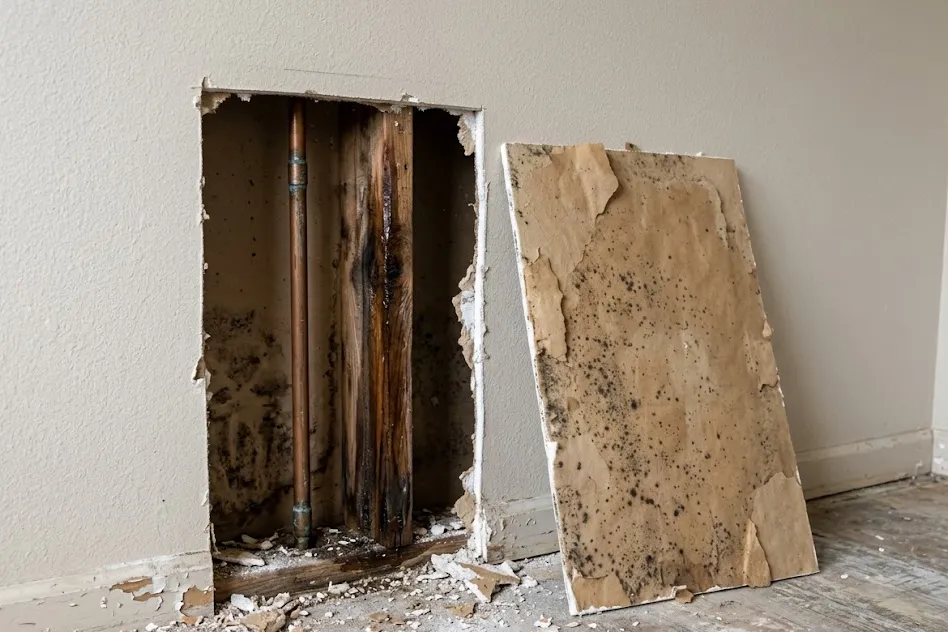
- Photograph before you clean. List the damaged property, take photos or video before any repair, and keep damaged items until the adjuster has seen them (Texas Department of Insurance). After a flood, FEMA also asks you to keep samples, such as a piece of carpet (FloodSmart).
- Make temporary repairs and keep receipts. California warns that a policy may not cover further damage if you did not take reasonable steps to protect the property, and says insurers reimburse reasonable temporary repair costs if you save the receipts. Don’t make extensive permanent repairs until the adjuster has been to your home and assessed the damage (California Department of Insurance).
- Use the right professional. In Texas, a mold remediation claim needs a state-licensed mold professional, an inspection showing the mold was removed and its cause fixed, and a certificate that the mold was removed (Texas Department of Insurance). Other states have their own rules.
- Separate the mold costs. Insurance.com suggests making sure only mold-related charges count against the mold limit: if a floor costs $2 per square foot to replace normally and $2.50 with mold, only the extra $0.50 should go against the mold limit, with the rest under your dwelling coverage (Insurance.com).
How to avoid a denial, and what to do after one
Most denials come back to timing and cause. The EPA says to dry water-damaged areas and items within 24 to 48 hours to prevent mold growth (EPA), and Washington’s regulator warns that insurance won’t cover water damage if you delay roof repairs after a storm (Washington OIC). Experian, citing the nonprofit United Policyholders, suggests keeping records and receipts of what you did to prevent mold, photographing the damage and your cleanup, and not suggesting a cause or agreeing with the insurer about one until its investigation is complete (Experian).
If a claim is denied, the reason matters. In California, a denial must be in writing, give specific reasons, and tell you that the Department of Insurance can review it if you believe it was wrong; the department also suggests raising your concerns with the claims manager first, with copies of your documents (California Department of Insurance). NerdWallet notes that an appeal usually means proving the mold came from a sudden event rather than gradual damage (NerdWallet). Your state insurance department’s consumer line is the place to ask how the process works where you live.
When to call a public adjuster
A public adjuster is hired by you, not the insurer, to negotiate your claim for a fee, and states license and limit them:
- Texas: fees of up to 10% of the total amount the company pays, which can be based on the whole settlement rather than only the disputed part; you may still owe the fee if the offer doesn’t rise, you can cancel within 72 hours of signing, and a public adjuster can’t act as your contractor (Texas Department of Insurance).
- Florida: after a disaster with a state of emergency declared by the Governor, fees are limited to 10% of the claim payment for one year, then 20%; adjusters can’t charge on payments made before you signed with them, and you can cancel within 10 business days (Florida DFS).
Our estimate: on a mold claim capped at $5,000, a 10% fee would be $500. Because mold limits are low, the fee is easiest to justify when mold is only one part of a larger water damage claim. This is our arithmetic on the figures above, not advice about any particular claim.
What the EPA and CDC say about health
Inhaling or touching mold or mold spores may cause allergic reactions in sensitive people, with hay fever-type symptoms such as sneezing, runny nose, red eyes and skin rash (EPA). The CDC says exposure to damp and moldy environments may cause a variety of health effects or none at all, that people with asthma or mold allergies may have severe reactions, and that people with weakened immune systems or chronic lung disease may get lung infections from mold (CDC, September 2024). This is general information, not medical advice; if someone in the home has symptoms, talk to a health professional.
How to keep the bill down
- Dry leaks and wet materials within 24 to 48 hours; it keeps mold from starting and keeps the claim about a sudden event (EPA).
- Keep indoor humidity below 60%, ideally 30% to 50% (EPA); the CDC suggests no higher than 50% (CDC).
- Replace hoses to the washer, dishwasher and other appliances; the Insurance Information Institute suggests every five years (Triple-I).
- Read the mold, water backup and seepage wording in your policy now, before a loss, and price an endorsement if the limit is low.
- Fix damp crawl spaces at the source; our guide to crawl space encapsulation cost covers that work.
- Get estimates from at least three remediation companies and check that each includes the same testing, cleanup and containment (HomeGuide).
Questions to ask before you sign
- To your insurer: Is mold covered when it follows a covered water loss, and what is the mold limit and deductible?
- To your insurer: Does the mold limit include testing, cleanup and the rebuild, or only the removal?
- To your insurer: Can I add a mold, water backup or hidden water damage endorsement, and at what price?
- To the remediation company: Will you document the source of the water and the extent of the mold for the adjuster?
- To the remediation company: Does your estimate separate mold removal from ordinary water damage repairs?
- To the remediation company: Do you hold the license my state requires, and will you provide a clearance report when the work is done?
- To a public adjuster: What is your fee, can you state it in dollars, and how do I cancel the contract?
Sources
- Texas Department of Insurance, When are water damage and mold covered by insurance?, last updated April 24, 2025.
- Texas Department of Insurance, Public adjusters: What to know before you hire one, last updated March 25, 2025.
- California Department of Insurance, Residential Property Claims Guide, updated February 27, 2025.
- Washington Office of the Insurance Commissioner, Leaks, water damage and mold, undated, checked October 2026.
- Florida Department of Financial Services, Homeowners Insurance Policy Endorsements, undated, checked October 2026.
- Florida Department of Financial Services, Public Adjusters, undated, checked October 2026.
- National Association of Insurance Commissioners, What is an Insurance Endorsement or Rider?, August 22, 2019 (older page).
- Insurance Information Institute, Protecting your home from mold, Which disasters are covered by homeowners insurance? and Renters Insurance, undated, checked October 2026.
- FEMA National Flood Insurance Program, Flood Recovery Checklist and What Is Covered by a Flood Insurance Policy for Homeowners?, undated, checked October 2026; NFIP Claims Handbook, August 2024 (older guide).
- Washington State Department of Health, Renters, Landlords, and Mold, undated, checked October 2026.
- U.S. Environmental Protection Agency, A Brief Guide to Mold, Moisture and Your Home, last updated February 18, 2026.
- Centers for Disease Control and Prevention, Mold, September 26, 2024.
- NerdWallet, Does Homeowners Insurance Cover Mold?, updated June 11, 2026.
- Insurance.com, Does homeowners insurance cover mold?, last updated January 22, 2026.
- Experian, Does Homeowners Insurance Cover Mold?, September 9, 2026.
- HomeGuide, How Much Does Mold Removal and Remediation Cost?, February 5, 2026.
- Fixr, Mold Remediation Cost, updated August 29, 2025.
- This Old House, How Much Does Mold Remediation Cost? (2026 Guide), updated March 11, 2026; cost data sourced from Angi.